Mortgage Rate Trends Reach Three-Week High Amid Stable Market Conditions
Mortgage rates have shown resilience despite moderate increases at the start of the new week, continuing a pattern of modest declines observed over the past few trading sessions. The most significant development is that any three consecutive business days now represent the lowest rates seen since September 23rd, suggesting a period of relative calm in the borrowing landscape.
Analysts note that the recent rate movements lack clear catalysts tied to specific economic reports or breaking news headlines. This absence of direct drivers means the broader market sentiment has become a more prominent factor influencing mortgage pricing. As traders seek safer havens amid concerns about potential tech sector pullbacks, the same sentiment continues to shape interest rate dynamics across the housing market.
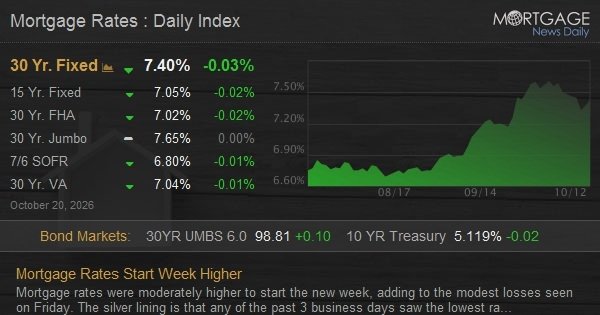
The latest data reveals that the average top-tier 30-year fixed mortgage rate has risen to 7.43%, marking a 0.06% increase compared to Friday’s levels and a 0.10% rise above Thursday’s low point of 7.33%. These figures indicate a gradual but steady uptick in borrowing costs for long-term homebuyers.
Current Mortgage Rate Landscape
With rates hovering near recent highs, borrowers should carefully evaluate whether refinancing or securing new mortgages makes sense given the prevailing conditions. The 7.43% average reflects persistent demand for capital preservation as investors navigate uncertain economic outlooks.
Key Rate Metrics and Historical Context
The 30-year fixed-rate benchmark serves as a critical reference point for homeowners and lenders alike. At 7.43%, this rate sits above the historical average for the past year while remaining below the peak levels recorded during earlier volatility periods. The recent climb represents a meaningful shift from the relatively stable environment experienced in previous months.
When comparing against the past three business days, the current rate stands out as the highest among them, reinforcing the notion that borrowing costs have been gradually increasing throughout the week. This upward trajectory suggests that market participants may be adjusting expectations regarding future rate movements.
Market Sentiment Driving Borrowing Decisions
“Broad market sentiment” has emerged as a dominant force shaping mortgage activity, particularly because major economic events remain sparse on the calendar. Without significant fiscal announcements, employment data releases, or inflation reports to disrupt normal patterns, investor behavior tends to gravitate toward safety.
This sentiment dynamic creates a self-reinforcing cycle where uncertainty about technology sector performance prompts capital flight into traditional safe-haven assets, including government bonds. As bond yields adjust downward in response to these shifts, mortgage rates follow suit, contributing to the observed stabilization in borrowing costs.
Tech Sector Volatility and Its Ripple Effects
While tech stocks achieved their strongest performance in several weeks, the underlying market anxiety remains palpable. The sector’s sensitivity to macroeconomic developments means that even minor corrections can trigger broader risk-off positioning across the investment community.
Traders’ pursuit of stability has amplified the impact of broad market movements on mortgage pricing. When equity markets experience volatility, the correlation between those swings and fixed-rate mortgage spreads often intensifies, making it difficult for borrowers to find favorable terms regardless of individual credit profiles.
Implications for Homeowners and Lenders
For existing homeowners considering refinancing, the current rate environment presents both opportunities and challenges. While slightly lower rates than last month would have made refinancing more attractive, the overall upward trend indicates that waiting for further decreases may not yield substantial savings.
Lenders operating in the mortgage sector must adapt to the evolving rate landscape by maintaining competitive product offerings and transparent communication with applicants. The continued presence of strong demand for capital preservation suggests that loan origination volumes may remain robust despite rising cost-of-capital environments.
Practical Considerations for Borrowers
Homebuyers and prospective refinancers should weigh the trade-offs between current rates and potential future adjustments. If locking in a mortgage at today’s levels proves advantageous, doing so before rates potentially rise further could provide meaningful financial benefit.
Conversely, those who anticipate rate declines in the coming months might consider delaying financing decisions until clearer signals emerge. The absence of immediate economic catalysts suggests that short-term fluctuations may persist, allowing borrowers flexibility in timing their commitments.
Regardless of personal circumstances, staying informed about rate trends remains essential. The mortgage market operates on complex feedback loops where changes in one segment can quickly propagate through the entire system, affecting everything from monthly payments to overall housing affordability.
As the week progresses and major economic events remain absent from the calendar, the influence of broad market sentiment will likely continue to dominate rate movements. This environment favors caution rather than aggressive price-taking, encouraging both lenders and borrowers to approach mortgage decisions methodically.
Recommended Actions:
- Review current mortgage offers against alternative financing options
- Consider locking in rates if favorable terms align with your financial goals
- Monitor upcoming economic releases that could affect rate trajectories
- Consult with financial advisors to assess how rate changes might impact your overall strategy
Understanding the interplay between market sentiment, economic indicators, and borrowing costs remains crucial for anyone navigating the mortgage landscape. The current situation reflects a balanced equilibrium where neither extreme gains nor losses appear imminent, though careful analysis is always warranted.
In summary, the mortgage rate environment continues to evolve with notable nuances. While the 30-year fixed rate sits at 7.43%—the highest among the past three business days—the absence of dramatic economic shocks allows for measured decision-making. Borrowers and lenders alike should maintain vigilance, recognizing that even subtle shifts in market psychology can significantly influence borrowing costs in the medium term.
Real Estate, Finance, News, Business, Economy, Housing Market, Interest Rates, Mortgage Rates, Economic Indicators, Financial Markets