Open Enrollment 2025: What You Need to Know About Health Insurance Premiums Right Now
The 2025 health insurance open enrollment season has officially begun, and for millions of Americans shopping for coverage on the Affordable Care Act (ACA) Marketplace, through Medicare, or via employer-sponsored plans, the central question remains the same: how much will premiums cost, and what factors drive those numbers? With enhanced subsidies extended through 2025 under the Inflation Reduction Act, a shifting insurer landscape, and persistent medical inflation, this year’s enrollment window carries significant financial implications for households across the income spectrum.
Key Dates and Deadlines You Cannot Miss
Timing varies depending on where you get coverage. Missing a deadline can mean a full year without insurance or locked into a plan that no longer fits your needs.
| Coverage Type | Open Enrollment Period | Coverage Start Date |
|---|---|---|
| ACA Marketplace (HealthCare.gov & most state exchanges) | Nov 1, 2024 – Jan 15, 2025 | Jan 1, 2025 (if enrolled by Dec 15); Feb 1, 2025 (if enrolled Dec 16 – Jan 15) |
| Medicare | Oct 15 – Dec 7, 2024 | Jan 1, 2025 |
| Employer-Sponsored Plans | Typically 2–4 weeks in Oct–Nov (set by employer) | Usually Jan 1, 2025 |
| Medicaid / CHIP | Year-round (no fixed enrollment window) | Varies by state |
Note: Several state-based exchanges — including California, New York, New Jersey, Rhode Island, and the District of Columbia — have extended deadlines beyond January 15. Check your state’s marketplace for exact dates.
Premium Trends for 2025: What the Data Shows
According to KFF (Kaiser Family Foundation) analysis of rate filings across the individual market, the average premium increase for benchmark Silver plans in 2025 is approximately 4–6% nationally — moderating from the 7–8% increases seen in 2023 and 2024. However, averages mask wide variation:
- Lowest increases: States like Indiana, Michigan, and New Mexico saw average rate changes near 0–2%, driven by robust insurer competition and stable risk pools.
- Highest increases: Parts of Alaska, Wyoming, and rural Georgia face double-digit hikes (10–18%) due to limited carrier participation and higher healthcare utilization.
- New entrants: Insurers such as Oscar Health, Friday Health Plans (in select markets), and regional Blues plans expanded into new counties, adding competitive pressure in some areas.
- Exits: Bright Health and Cigna (in certain individual markets) continued retrenchment, reducing choice in some rural regions.
Context: Premiums reflect the total cost of the plan before subsidies. For the roughly 90% of Marketplace enrollees who qualify for Advanced Premium Tax Credits (APTC), net out-of-pocket premium costs often remain low or even $0 — especially for those earning under 250% of the federal poverty level (FPL).
The Subsidy Cliff Is Gone — For Now
One of the most consequential policy developments for 2025 is the continuation of enhanced ACA subsidies originally enacted in the American Rescue Plan (2021) and extended through 2025 by the Inflation Reduction Act (2022). These provisions:
- Eliminate the “subsidy cliff” that previously cut off assistance at 400% FPL (~$58,320 for an individual in 2024).
- Cap benchmark Silver plan premiums at no more than 8.5% of household income for those above 400% FPL.
- Increase subsidy generosity for lower-income enrollees, many of whom qualify for $0-premium plans after tax credits.
Without congressional action, these enhanced subsidies expire after 2025. If they lapse, KFF estimates roughly 3.7 million people could lose coverage due to unaffordability, and average net premiums for subsidized enrollees would rise by an estimated 53%.
Medicare 2025: Part B, Part D, and the $2,000 Cap
For the 66 million Americans on Medicare, 2025 brings notable changes beyond standard premium adjustments:
- Part B standard premium: $174.70/month (up from $174.40 in 2024 — a modest $0.30 increase). Higher-income beneficiaries pay more via IRMAA surcharges.
- Part D prescription drug overhaul: The Inflation Reduction Act introduces a $2,000 annual out-of-pocket cap on covered Part D drugs — a landmark change eliminating catastrophic-phase cost-sharing.
- Insulin cap: Monthly insulin cost-sharing remains capped at $35 for all Part D plans.
- Medicare Advantage (Part C): Average premiums projected to decline slightly (~$18/month), but plan benefit designs vary widely; review Annual Notice of Change (ANOC) packets carefully.
Employer Coverage: What Workers Should Watch
Roughly 153 million Americans get insurance through an employer. While employers set their own enrollment windows, several trends shape 2025 offerings:
- Average family premium: $23,968 annually (2024 KFF Employer Health Benefits Survey), with workers contributing ~$6,575 on average.
- High-deductible health plans (HDHPs) paired with HSAs continue to dominate; 55% of covered workers are in HDHPs.
- Narrow networks & tiered plans: More employers offer “value-based” or “accountable care” networks with lower premiums but restricted provider choice.
- Wellness incentives: Premium discounts for biometric screenings, health risk assessments, or digital health engagement are increasingly common.
Action item: Compare your employer’s total cost (premium + deductible + out-of-pocket max) against a Marketplace plan if you’re eligible for subsidies. In some cases, especially for lower-wage workers at large firms, the Marketplace may be cheaper — though you’d lose employer contribution.
How to Shop Smarter: 5 Steps Before You Enroll
- Update your income & household info. Subsidies are based on 2025 projected income. Underestimating can trigger repayment at tax time; overestimating leaves money on the table.
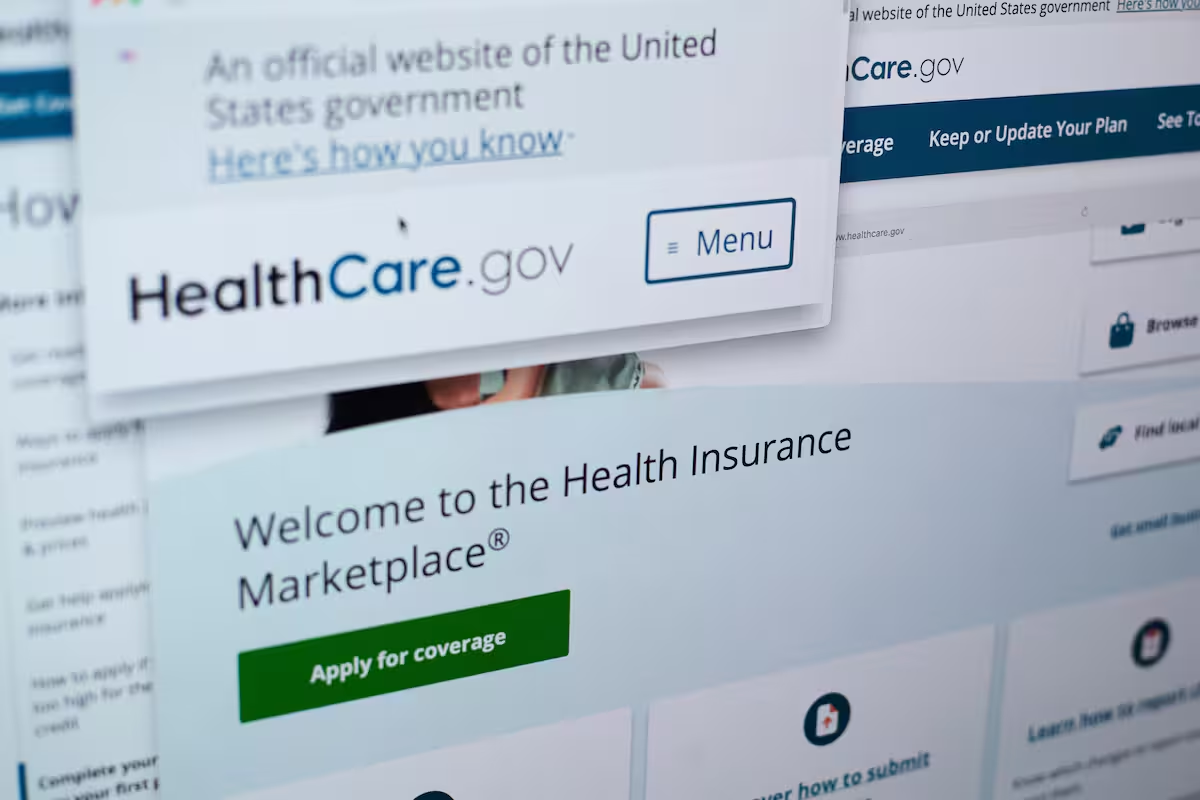
- Check provider networks & drug formularies. A low premium means little if your doctor or medication isn’t covered. Use HealthCare.gov’s doctor/prescription lookup or insurer portals.
- Compare total cost of care, not just premium. Add deductible, copays, coinsurance, and out-of-pocket maximum. A Bronze plan with a $7,500 deductible may cost more than a Silver plan with $3,000 deductible if you need regular care.
- Look for “CSR” Silver plans. If your income is 100–250% FPL, Cost-Sharing Reductions (CSR) are only available on Silver plans — they lower deductibles and copays dramatically.
- Don’t auto-renew blindly. Plan benefits, networks, and formularies change yearly. Even if you like your plan, confirm it still fits.
Special Enrollment Periods: Life Happens Outside Open Enrollment
If you miss the window, qualifying life events (QLEs) trigger a 60-day Special Enrollment Period (SEP) for ACA plans:
- Loss of other coverage (job loss, aging off parent’s plan, Medicaid disenrollment)
- Marriage, divorce, birth, adoption
- Permanent move to a new coverage area
- Change in immigration status
- Income change affecting subsidy eligibility
Medicare has its own SEP rules, including a 5-star SEP (Dec 8 – Nov 30) allowing one switch to a 5-star Advantage plan.
Where to Get Help — Free, Unbiased Assistance
Navigating plan choices can be overwhelming. Free, federally funded help is available:
- Navigators & Certified Application Counselors: Find local help at localhelp.healthcare.gov.
- State Health Insurance Assistance Programs (SHIP): Free Medicare counseling — shiphelp.org.
- Marketplace Call Center: 1-800-318-2596 (24/7, multiple languages).
- Employer HR/Benefits teams: For workplace plans, start here.
Avoid: Unsolicited calls, “licensed agents” pushing specific plans without comparing options, or websites mimicking HealthCare.gov.
Looking Ahead: The 2026 Uncertainty
While 2025 enrollment proceeds under current law, the policy environment remains fluid. Key questions for the next cycle:
- Will Congress extend enhanced ACA subsidies beyond 2025?
- How will Medicare drug price negotiation (first 10 drugs selected, prices effective 2026) affect Part D premiums?
- Will more states adopt public options or state-based reinsurance to stabilize markets?
- How will post-pandemic Medicaid unwinding (12+ million disenrolled as of late 2024) affect the individual market risk pool?
For now, the window is open. The smartest move is to log in, compare, and decide — before the deadline decides for you.
Business, Finance, Government, Health, News, Insurance, Healthcare, Affordable Care Act, Medicare, Health Insurance Marketplace, Open Enrollment, Premium Tax Credits, Inflation Reduction Act, Kaiser Family Foundation, HealthCare.gov, Employer-Sponsored Insurance, Health Savings Account, Cost-Sharing Reductions, Special Enrollment Period, Medicaid Unwinding, Drug Price Negotiation, Public Option, Reinsurance, Subsidy Cliff, Out-of-Pocket Maximum, Benchmark Silver Plan, Advanced Premium Tax Credits, Income-Based Subsidies, Federal Poverty Level, IRMAA, Part D Coverage Gap, Insulin Price Cap, Annual Notice of Change, Navigator Program, SHIP Counseling, Health Insurance Literacy, Consumer Protection, Healthcare Affordability, Policy Analysis, United States, 2025 Coverage Year