GameStop Stock: Analyzing the Recent Rally and the 61% Valuation Gap
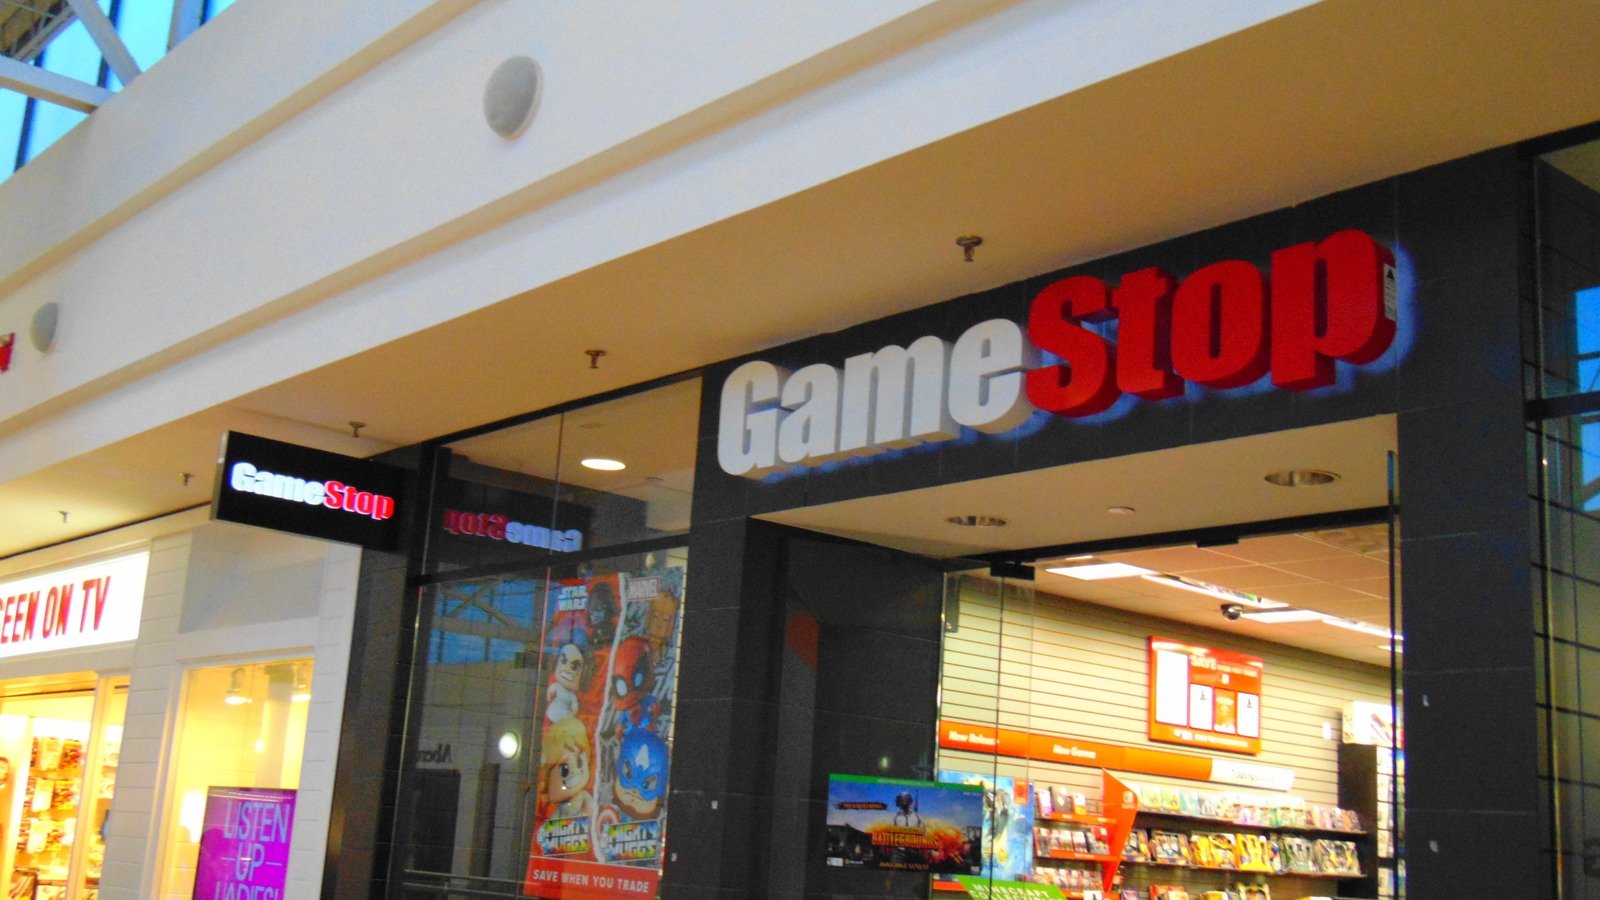
GameStop (GME) has once again captured the attention of investors, with its share price closing at US$24.58 on 4 October 2026. Recent performance has been a mixed bag, with short-term declines masking stronger gains over the past month and quarter. This divergence highlights the challenge of timing the market and the influence of shifting sentiment on a stock that has historically been a favorite among retail traders. In this analysis, we examine the recent price action, the bullish narrative that sees significant upside, the risks involved, and what it all means for investors considering a position.
Recent Price Action: A Tale of Two Timeframes
GameStop’s stock has experienced notable volatility in the weeks leading up to its 4 October 2026 close. While the share price edged down slightly over the past day and week, the broader trend over the past month tells a different story. This kind of divergence is common in stocks driven by sentiment, where short-term noise can overshadow underlying momentum.
What the Numbers Show
| Period | Return |
|---|---|
| Past Day | -0.7% |
| Past Week | -0.3% |
| Past Month | +28.3% |
| Past 3 Months | +12.0% |
| Year to Date | +19.2% |
| 1 Year (Total Shareholder Return) | +0.7% |
The table above illustrates a key tension: the stock has surged over the past month and quarter, yet its longer-term returns remain modest. This pattern often signals a shift in market sentiment rather than a fundamental re-rating, at least so far.
The Bullish Narrative: Why Some See $63
Despite the modest one-year return, a significant portion of the market remains optimistic about GameStop’s prospects. The most followed fair value narrative on Simply Wall St places the stock’s intrinsic value at $63 per share, implying a 61% undervaluation relative to its last close of $24.58. This gap suggests that if the bullish thesis plays out, early investors could see substantial upside.
The Path to Higher Margins
GameStop will increase profit margins as it scales higher margin collectibles and digital businesses, while keeping a tight handle on costs. That combination of better mix and expense control could lift profitability much faster than top line revenue suggests, even if sales only grow in the low double digits each year.
This outlook hinges on GameStop successfully transitioning from a traditional video game retailer to a broader entertainment and collectibles platform. The company has been investing in digital sales, NFTs, and trading card operations, which carry higher margins than its legacy hardware and software sales. If these initiatives gain traction, the overall profitability could improve dramatically, justifying a higher valuation.
Key Risks That Could Unravel the Thesis
While the potential rewards are tempting, the GameStop investment thesis carries significant risks. The stock’s history is marked by extreme volatility driven by social media sentiment and retail trading frenzies, rather than consistent fundamental performance. Any shift in investor mood could quickly erase recent gains.
Execution and Market Risks
The company’s transformation plans face several hurdles. Competition in the gaming and collectibles space is intense, with established players like Amazon, eBay, and specialty retailers. Moreover, the success of digital initiatives depends on consumer adoption and technological execution—areas where GameStop has historically struggled. If profitability fails to materialize as projected, the $63 fair value would be unsustainable, and the stock could revert to lower levels.
Navigating the GameStop Opportunity
For investors considering GameStop, the current environment presents both opportunity and danger. The 30-day rebound and positive year-to-date return suggest that momentum is on the bull’s side, but the stock’s ability to sustain this trend depends on tangible progress in its business transformation.
What Investors Should Consider
Before jumping in, investors should ask themselves whether they are comfortable with the level of risk associated with meme stocks. It is essential to scrutinize the company’s financial statements, monitor updates on its digital strategy, and be prepared for sharp price swings. Diversification and position sizing are critical when dealing with stocks of this nature.
Conclusion: Balancing Sentiment and Fundamentals
GameStop’s recent performance underscores the powerful influence of market sentiment, but the long-term investment case rests on the company’s ability to execute its transformation and deliver sustainable profitability. While the valuation gap to the $63 fair value narrative is tempting, it remains to be seen whether the business can support such an optimistic outlook. Investors should approach with caution, grounding decisions in thorough research rather than hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Business, Finance, Games, Shopping, Internet, Electronics, News, Stock Market, Investment Analysis, Meme Stocks, Retail Investing, Video Game Retail, US Stocks