Global Semiconductor Stocks Fall as AI Buildout Fears and Higher Rates Hit Hard
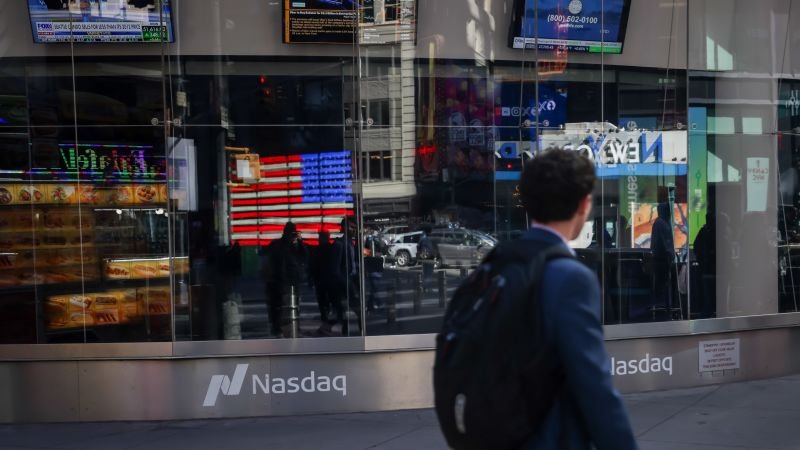
A global rout in semiconductor chip stocks continued on Thursday, sending investors further into defensive positions as concerns about the AI buildout, soaring borrowing costs, and geopolitical tensions intensify. The S&P 500 managed a modest bounce, rising 0.33% on Thursday, while the Dow Jones Industrial Average climbed 1.08% and the Nasdaq Composite edged up 0.08%. Yet the most dramatic move came in the chip sector itself, where the closely watched index of semiconductor stocks slipped 0.88% for the seventh straight day, reflecting lingering uncertainties about how quickly artificial intelligence infrastructure projects will materialize and whether companies can sustain explosive growth amid tightening monetary conditions.
Rising Rates and AI Debt Unsettle Investors
The sharp decline in chip stocks follows a sharp sell-off on Wall Street Wednesday, when a strong U.S. inflation report amplified fears that rising interest rates will make it increasingly expensive for companies to fund the massive AI infrastructure buildout. Many AI-first firms are already burdened by substantial debt loads, and investors are watching closely as the trajectory of leading frontier labs shows signs of cooling. Analyst Neil Wilson of Saxo Investment Group captured the mood of market anxiety, noting that worries about AI deployment bottlenecks, elevated valuations, disappointing earnings growth at top U.S. AI companies, Chinese competition, inflation pressures, and rate hikes have pushed investors toward safer havens. The combined effect of these factors created a perfect storm that sent chip-related equities sliding even as broader indices held relatively steady.
Chip Stocks Face Pressure from Geopolitical Tensions
Beyond the broader AI narrative, regional markets have reacted strongly to supply chain disruptions and strategic rivalries. South Korea’s KOSPI Index plummeted 7.6% on Thursday, finishing among the steepest declines in Asia, while Japan’s Nikkei Composite dropped 4.9% and Hong Kong’s Hang Seng Index fell 1%. The heavy weighting of chipmakers in these markets—particularly South Korea’s SK Hynix and Samsung Electronics—made the region especially sensitive to production halts and export restrictions. In Taiwan, where TSMC operates its manufacturing facilities, the company’s shares fell 2% despite bumper earnings reported late Thursday, underscoring how cyclical exposure to global demand remains a persistent risk for the industry. These regional swings highlight the vulnerability of semiconductor producers to both domestic policy shifts and international trade dynamics.
The AI Buildout Uncertainty Drives Volatility
At the heart of the chip sector’s turmoil lies the question of whether the anticipated surge in artificial intelligence infrastructure spending will materialize at the projected pace. Valuations for frontier AI companies have been notoriously volatile throughout the past year, and many remain privately held, forcing investors to look outward for clues about demand. Recent reports indicate that leading AI labs are experiencing slower-than-expected growth. For instance, Anthropic disclosed that its sales grew 45% to $17 billion in the last quarter alone, with second-quarter growth more than doubling. While these numbers suggest continued momentum, the broader picture reveals a deceleration in enthusiasm. Multiple news outlets have reported that Anthropic, poised for an IPO in the near term, saw its quarterly sales rise dramatically yet face mounting pressure as competitors close in and capital allocation becomes harder to justify. Such signals have historically been enough to trigger sharp corrections in the sector, as seen in the seven-day slide of the chip index.
The uncertainty extends beyond individual companies to the entire ecosystem. Data center operators and specialized AI cloud providers have faced mounting scrutiny. Research from Gartner forecasted that over 80% of neocloud providers could cease operations by 2030 due to cost pressures and a lack of differentiated business models—a warning that resonates with investors who see the sector as potentially overvalued. Meanwhile, the political landscape surrounding data center construction adds another layer of unpredictability. With midterm elections approaching, investors are betting on an ambitious national buildout program, but any shift in policy direction—such as a Democratic victory in Congress—could negatively affect sector sentiment. This confluence of financial, technological, and geopolitical forces has created a volatile environment where even small shifts in sentiment can trigger outsized price movements.
Looking ahead, the market appears to be pricing in a cautious optimism tempered by skepticism. Analysts caution that while earnings seasons typically validate the strength of AI demand, the current climate makes such validation uncertain. The industry watchdog C.C. Wei, CEO of Taiwan Semiconductor Manufacturing Company (TSMC), offered a measured assessment during his earnings call, noting that rising component prices and macroeconomic uncertainty continue to challenge demand in certain market segments. Despite bumper results reported late Thursday, TSMC’s shares still fell 2%, contributing to the broader index decline. As the sector navigates these headwinds, investors will need to weigh short-term volatility against longer-term fundamentals, particularly as the next cycle of AI adoption unfolds and as central banks signal whether rate cuts might eventually restore confidence.
In summary, the semiconductor stock market remains in a state of flux, caught between the promise of transformative AI applications and the reality of high financing costs, geopolitical friction, and slowing growth indicators. The recent rout in chip stocks reflects a market that is deeply attuned to the interplay between technological ambition and economic realities. Whether this period represents a temporary correction or a fundamental shift in the industry’s trajectory will depend on how quickly companies can demonstrate sustainable demand, manage debt burdens, and adapt to evolving regulatory landscapes. For now, the sector continues to test investors’ patience, reminding them that behind every headline lies a complex web of technical, financial, and geopolitical considerations.
Business, Technology, Finance, News, Industrial