Soaring Mortgage Rates Make Homeownership Harder Than Ever
The Current Crisis in Home Buying
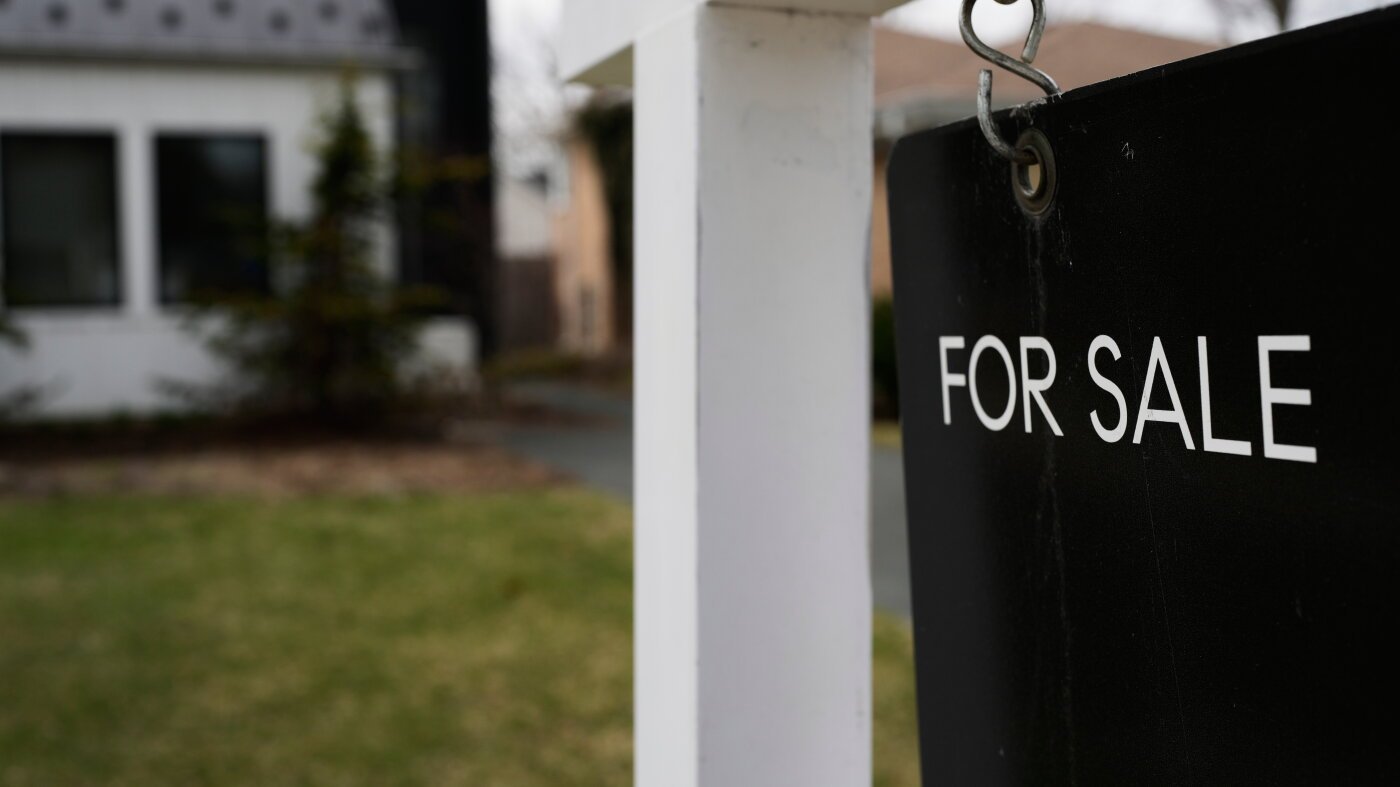
With average 30-year fixed mortgage rates sitting at 7.28 percent—nearly triple the levels seen during the pandemic—the American housing market faces unprecedented challenges. For many first-time buyers and existing homeowners looking to upgrade, the cost of borrowing has become a formidable barrier.
How High Rates Are Driving Up Monthly Payments
Take the example of a typical median-priced home. At current rates, a buyer could face roughly $900 more in monthly payments compared to when rates were around 3 percent during the pandemic era. That single figure illustrates how dramatically borrowing costs have shifted, squeezing household budgets and delaying major life milestones.
Federal Reserve Policy and Its Ripple Effects
The surge in mortgage rates stems largely from Federal Reserve actions aimed at cooling inflation. After the U.S. conflict with Iran spooked bond markets and heightened concerns about price pressures, the central bank has continued raising interest rates throughout the year. These moves push borrowing costs higher across the board—not just for homes, but for cars, student loans, and other consumer debt.
Beyond Mortgages: Auto Loans and Student Debt
Higher borrowing costs extend beyond housing. Four-year auto loans are approximately three percentage points more expensive today than they were at the start of 2022—a period when pandemic-era low rates made car financing nearly affordable. Similarly, student loan payments have risen alongside other forms of credit, compounding financial strain for young adults.
Real Lives Affected by the Rate Hike
Personal stories bring the abstract numbers to life. Carrie Goldstein, a woman living in a Cleveland suburb, had dreamed of relocating to Rocky River—a walkable community with a charming downtown and lakefront access. Yet the prohibitive mortgage costs proved insurmountable. “It just became more and more disheartening when I did the math,” she explained. “It’s just not in the cards.”
Her experience mirrors that of countless others. While some homeowners have delayed selling or refinancing, others have chosen to stay put indefinitely. The combination of high housing prices and elevated borrowing costs has created a perfect storm for families trying to build equity.
What This Means for the Broader Economy
The ripple effects of higher rates reach far beyond individual mortgages. Increased borrowing costs reduce consumer spending power, which can slow economic growth. Meanwhile, businesses face higher financing expenses, potentially leading to reduced investment and hiring freezes. The overall picture suggests that while the Fed’s tightening measures aim to curb inflation, they simultaneously create significant headwinds for household finances.
Looking Ahead
As policymakers weigh further adjustments to monetary policy, the immediate challenge for buyers remains stark. With rates at historic highs and no guarantee of reversal, the path forward requires careful navigation. For those currently on the fence about purchasing a home, the message is clear: patience may be the best strategy until the economic landscape stabilizes.
Understanding these dynamics helps readers make informed decisions. Whether you’re a prospective homeowner, a lender, or simply curious about the forces shaping modern finance, the story of rising rates offers valuable insight into the interconnected nature of our economy.
Finance, Real Estate, Home, Economy, Business, People, News, Society